The Human Advantage: 5 Talent Strategy Lessons from FutureWorks 2026

By Alexis Medina
Director of Client Delivery

I recently had the opportunity to attend Indeed’s FutureWorks 2026 conference, where talent leaders, economists, and industry experts came together to explore the forces shaping the future of work. AI understandably dominated many of the conversations, but one of my biggest takeaways from the conference wasn’t about technology. It was about people—and whether employers will have enough of them, with the right skills, to do the work ahead. 

Today’s U.S. labor market is often described as “low-hire, low-fire,” with employers remaining cautious about adding headcount while layoffs and quits are also relatively minimal. But beneath that relative stability is a longer-term challenge: labor supply. Aging populations, retirements, reduced labor force participation, and skills mismatches are creating pressure within the available workforce, while demand for more skilled and senior talent continues to grow.  

At the same time, AI has changed what people can accomplish, how candidates and employers are evaluating each other, and how recruiters are spending their time.  

Taken together, these shifts should change the question talent leaders are asking from “How will AI replace work?” to, “How can we use technology to expand what people can do—while finding, attracting, and keeping the talent the future of work requires?” 

Here are five key concepts discussed at FutureWorks that talent leaders can use to shape their workforce planning.  

1. A slower hiring market doesn’t mean talent is easy to find. 

When hiring slows, it’s easy to assume recruiting should be easier. More available candidates plus fewer open jobs should mean less competition for talent, right? 

Not necessarily. 

National labor market data can tell us a lot about the overall environment, but it can’t tell an employer whether the right person exists for a specific role, skill set, shift, wage, or location. FutureWorks highlighted that demand isn’t shifting uniformly. Competition remains stronger for certain skills and more senior talent even as other parts of the market stay relatively flat.  

That distinction matters because the obstacle to successful hiring isn’t always at the top of the funnel.  

Before investing more in attraction strategies, employers should diagnose where the constraint actually sits. Do enough people know about the opportunity? Are qualified candidates interested but dropping out? Have job requirements narrowed the available pool unnecessarily? Or is there genuinely not enough talent with the required capabilities in that market? 

Each of those challenges requires a different response—from stronger attraction or process improvements to rethinking requirements or addressing a true supply gap. 

For talent leaders, that means looking below the macro headlines. Local market data, role-level supply and demand, compensation, schedules, and candidate behavior can tell a very different story from national hiring trends. 

Flat demand doesn’t mean unlimited talent. And when supply is the real constraint, simply sourcing harder won’t solve it. 

2. Expand the talent pool by rethinking role requirements. 

One question came up repeatedly at FutureWorks: What does someone truly need to bring to the job on Day 1, and what can the employer teach them once they’re there? It’s a simple question with potentially significant implications for talent supply. 

Job descriptions have a tendency to accumulate requirements over time. Experience in a particular industry. Familiarity with a specific system. A certain number of years in an equivalent role. A credential that may have historically been useful but isn’t necessarily predictive of someone’s success today. 

In a tightening labor market, every role requirement has a cost: it removes people from the potential talent pool. 

That doesn’t mean compromising on talent quality. It means being more precise about which requirements are truly necessary. FutureWorks attendees were challenged to look at what candidates can do in practice rather than relying solely on what appears on paper.  

Consider a hard-to-fill technician position. An employer may traditionally look for someone who has already performed that exact job in the same industry. But often, industry-specific knowledge can be taught. Someone with a strong mechanical foundation, problem-solving ability, and willingness to learn is likely to succeed in the role, even if they haven’t held the specific job title before.  

That’s where skills-first hiring becomes more than a sourcing tactic. It becomes a workforce strategy. Hire for what must be present. Train what can be built. 

3. Use AI to return capacity—not simply increase output.  

One of the AI themes explored in FutureWorks sessions that resonated most with me was the importance of using AI to create capacity. Put simply: Don’t give people more work. Give them more tools. 

The AI in recruiting conversation often begins with automation: Which tasks can the technology perform? How much time would be saved by automating those tasks? What additional output can we generate?  

Those are useful questions, but I think there’s another one that matters just as much: What do we want people to do with the capacity AI gives back to them? 

If AI or an automated workflow saves a recruiter 10 hours each week and we immediately fill those 10 hours with more administrative work, we’ve increased throughput, not value. 

The greater opportunity is to use technology to absorb repeatable tasks so people can spend more time on work that benefits from human judgment—relationship building, strategy, creativity, and problem-solving. In talent acquisition, technology can and should support activities like scheduling, screening, and content development while creating more room for meaningful human interaction.  

Surprisingly, despite the enormous amount of conversation about AI among TA practitioners, employers still aren’t adopting it consistently—or aren’t talking openly about it with candidates. Indeed Hiring Lab reported that only 6% of U.S. job postings mentioned AI or an adjacent keyword as of July 2026, and PeopleScout’s recent candidate experience research found 65% of candidates heard nothing about AI from any employer they applied to. This suggests that many organizations are still determining where and how AI fits into their recruitment process, which creates an opportunity to be intentional about adoption. 

Instead of starting with “What can we automate?” talent leaders should be asking “Where could technology return capacity to our people—and where would we create the most value by reinvesting that time?” 

The goal isn’t more work. It’s more capacity for the work that matters. 

4. AI is reshaping your employer brand narrative. 

Traditionally, candidates have visited the employer’s career site, read employee reviews, and searched social channels, to see what current and former employees say, evaluate the visibility and credibility of company leaders, and determine whether a company’s promise matches the lived employee experience. And so, for years, employers have invested in making their career sites easier to find, building compelling employer value propositions (EVPs), and creating recruitment marketing content that shows candidates what it’s like to work for them. 

But AI has changed search behavior, giving employers less control over their brand narrative. Instead of visiting a career site and navigating through employer-created content, a candidate can ask a specific question and receive an answer synthesized from multiple sources. The employer may no longer get the first—or only—opportunity to frame the story.  

Your employer brand isn’t only what you say about yourself. Increasingly, it’s what candidates—and the technology helping them research you—can verify. 

For talent leaders, this means broadening your employer brand efforts beyond the career site. Monitor reviews and third-party conversations. Consider leadership visibility and employee advocacy. Think about the questions candidates are likely to ask AI about your organization—and whether the answers they’ll find match the experience you’re promising. 

Recruitment marketing can create awareness, but it won’t compensate for a disconnect between the EVP and the lived employee experience. 

5. Consider your hiring process from the candidate’s perspective. 

Employers naturally measure recruitment outcomes from the organization’s perspective: How long did it take to fill the role? When did the candidate accept? When did they start? How quickly did the new hire become productive? 

At FutureWorks, we explored a small but distinct shift in perspective—measuring success from Apply to First Paycheck. 

For employers, an employee’s start date marks the beginning of productivity. But for the worker, particularly in hourly or high-volume roles, the economic benefit of taking the job doesn’t begin until the first paycheck arrives.  

This small shift illustrates a larger point: What changes when we design and measure the hiring experience from the candidate’s side rather than our own? 

Suddenly, process speed isn’t just an efficiency metric. Communication isn’t simply a recruiting task. Compensation, scheduling, flexibility, development opportunities, manager interactions, and job requirements aren’t separate considerations—they’re all part of the talent proposition. 

What does this mean for talent leaders? If candidate fallout is a challenge within your hiring process, it may not be a recruiting problem. 

Before investing in another source or adding more candidates to the top of the funnel, ask why people aren’t choosing—or staying with—the opportunity being offered. Is the schedule competitive? Is compensation aligned with the market? Are requirements unnecessarily restrictive? Is the process asking too much of candidates? Can they see a future for themselves in the organization? 

The goal isn’t simply to move candidates through the process faster. It’s to design an opportunity—and a hiring experience—that gives them a stronger reason to choose you. 

Designing for the human advantage 

The real value of a conference like FutureWorks isn’t any single trend, statistic, or new technology. It’s seeing the connections between the changes happening at the same time. 
 
Based on these key takeaways from FutureWorks, I challenge talent leaders to ask themselves these three questions: 

  • What do employees truly need to know or be able to do on Day 1—and what can be taught post-hire? 
  • What tasks should AI take off recruiters’ plates, and what higher-value work should replace it? 
  • Are we designing jobs and hiring experiences around the talent available today—or adapting hiring models built for a different labor market? 

Talent supply is tightening over the long term.  Candidates have more ways to evaluate employers. Expectations around trust, respect, and transparency are rising. And AI-powered tools are enabling people and teams to accomplish more with the capacity they already have.  

The opportunity is to redesign work so technology expands human capability—and redesign talent strategies to support tomorrow’s workforce. 
Q3 2026 U.S. labor market insights: The hiring slowdown and the rise of self-taught AI skills 

The U.S. labor market closed Q3 2026 adding jobs at a modest and uneven pace, but without the layoffs that usually come with a slowdown. July delivered the quarter’s only monthly decline, August beat forecasts by a wide margin, and September added just 29,000 jobs. After revisions, payroll growth averaged roughly 51,000 jobs a month. Unemployment ended the quarter where it began, at 4.2%, and layoffs stayed near historic lows.

The defining story of Q3 was a market that slowed down but didn’t get any easier for employers. Organizations added fewer workers but held on to the ones they had, and the skills they need most remain hard to find. Meanwhile, more workers are building AI skills on their own, faster than employers are training them.

Q3 2026 by the numbers

  • Unemployment: The rate dipped to 4.1% in July, held there in August, and rose back to 4.2% in September. The September increase came from more people joining the labor force rather than from rising layoffs, according to EY-Parthenon. Participation recovered to 61.8% after falling to 61.4% in July, its lowest level since early 2021.
  • Job creation: Payroll growth swung sharply from month to month. July was first reported as a loss of 23,000 jobs. August’s initial gain of 162,000 came in at nearly triple what was forecasted. September added 29,000, and revisions removed a combined 60,000 jobs from July and August, turning July into a 10,000-job loss in July, and making the three-month average roughly 51,000.
  • Wage growth: Annual wage growth cooled every month of the quarter, from 3.2% in July to 3.1% in August and 3.0% in September. With inflation around 3.4%, real wages are now falling behind.
  • Job openings: Openings were little changed at 7.4 million in June, while the hiring rate (3.4%) and quits rate (2%) stayed low, a sign of a market where few people are changing jobs.
  • Sector standouts: Construction and Manufacturing posted steady gains, with Manufacturing now up 72,000 jobs since December 2025. Leisure and Hospitality swung from a 40,000-job loss in July to a 62,000-job gain in August. Healthcare kept adding jobs, but well below its pace of the past year. Information and Financial Activities continued to shed jobs and have lost more than 200,000 combined since the start of the year.

Top 4 trends shaping Q3 2026

1. Slower hiring doesn’t mean easier hiring

Q3’s most important signal was what didn’t happen. Hiring slowed, but employers largely held on to their workforces. LinkedIn’s hiring rate was 6.5% lower than a year earlier in August and remains 25% below its pre-pandemic pace. Yet, initial jobless claims fell to 197,000 in September, and announced layoffs reached their lowest September level since 2022. EY-Parthenon described a labor market that has settled into a “lower-growth equilibrium,” where modest job gains are still enough to keep unemployment broadly stable.

These factors can make talent harder to find, not easier. Workers who have jobs are staying in them, and the pool of available workers is shrinking. The civilian labor force has declined since the end of 2025, according to Indeed Hiring Lab, and Baby Boomer retirements will remain at their peak through 2028, according to KPMG. For employers, that means fewer candidates moving between jobs and fewer new workers entering the market to replace them.

2. Healthcare’s engine downshifts

Healthcare and Social Assistance carried the labor market through Q2, but its pace slowed noticeably in Q3, with 22,600 jobs added in July, its smallest gain since February. With just 13,000 in August and 16,700 in September, the sector was well below its average of more than 30,000 a month over the past year.

Healthcare’s slowdown may reflect constraints on funding and labor supply more than a drop in demand. Economists on Indeed’s Labor Market Outlook panel named personal care, home health, and nursing among the occupations most likely to see the largest gains in job postings over the next year.

3. The white-collar squeeze lands on junior roles

Information and Financial Activities have shed more than 200,000 jobs combined since January. EY-Parthenon attributes the losses to cost-cutting, restructuring, and weak hiring demand, possibly tied to greater AI integration in work processes. Professional and Business Services lost jobs for three consecutive months.

The pressure falls hardest on early-career workers. Revelio Labs’ AI Labor Market Tracker found that, “Employment for younger workers in the most AI-exposed occupations is down by 20% relative to the least exposed occupations, since pre-ChatGPT — compared with just 6% for older workers.” Organizations that have adopted AI are growing their workforce faster than those that haven’t, but the gains are in senior roles (32%) rather than junior ones (6%).

The picture isn’t one of simple replacement. KPMG cautions that weak hiring for new college graduates is more a product of the current “low-hire, low-fire” market than a clear indication of AI eliminating jobs. Some employers are already reversing course, with organizations like Ford and IBM reportedly rehiring for the same or similar positions they eliminated because of AI.

4. The AI skills gap goes DIY

In Q1, the AI story was a training gap. In Q3, workers took things into their own hands. A ICIMS survey found 47% of job seekers worked on their AI skills in the past six months, up from 41% a year earlier. The share of those teaching themselves rose from 22% to 30%, while employer-provided training stayed flat at about 16%.

That self-teaching has limits, with 43% of workers saying their AI skills are behind what they need to stay competitive. More than half (52%) say they aren’t getting the AI training they need from their employer and only 22% of employers require AI training for all employees.

This is shaping how candidates choose employers—42% of job seekers said an employer offering AI training would be more attractive than a similar employer that didn’t, and 14% would accept lower pay in exchange for it.

What this means for TA leaders

Q3 delivered a market that is creating fewer jobs without making the talent employers need any easier to find. Talent strategies have to account for both.

Plan for a smaller talent pool. Low layoffs and a shrinking labor supply mean critical roles won’t fill faster just because hiring has cooled. When fewer candidates are available, keeping the talent you already have should become part of your hiring strategy. With wages not keeping up with the cost of living, Gartner research shows employees are prioritizing rewards that offer financial stability over work-life balance and career growth. Reviewing total rewards with that in mind can help organizations hold on to critical talent.

Don’t mistake Healthcare’s slowdown for easier hiring. Slower job growth in Healthcare appears to reflect pressure on funding and labor supply, not a surplus of clinical talent. Organizations that depend on clinical, allied health, or home care roles should keep investing in proactive pipelines and internal mobility pathways, and plan for further supply constraints.

Protect the early-career pipeline. If junior roles are the first to go in AI-impacted functions, organizations risk a shortage of the experienced talent they will need in five years. With major organizations reportedly rehiring for roles they cut because of AI, redesigning entry-level work is a safer bet than eliminating it. Early-career programs that develop both critical thinking and AI skills help close that gap.

Make AI training part of the offer. More workers are teaching themselves AI skills, and many weigh development opportunities when comparing employers. Building AI training into the employee value proposition can help organizations stand out to candidates and hold on to the employees they’ve invested in.

Q3 showed that a slower labor market isn’t necessarily an easier one to hire in. For talent leaders, the advantage will likely go to those who invest in retention, pipeline depth, and skills development to compete for the talent that remains hard to find.

PeopleScout Jobs Report Analysis – September 2026

September delivered a softer headline, but the underlying labor market remains more stable than the payroll number alone suggests. U.S. employers added 29,000 jobs, below expectations, while revisions reduced July and August payrolls by a combined 60,000. Unemployment edged up to 4.2%, labor force participation was little changed at 61.8%, and annual wage growth slowed to 3.0%. 

The numbers

  • 29,000: U.S. employers added 29,000 jobs in September.
  • 4.2%: The unemployment rate rose to 4.2% from 4.1%.
  • 3.0%: Wages increased 3.0% over the past year.

The good 

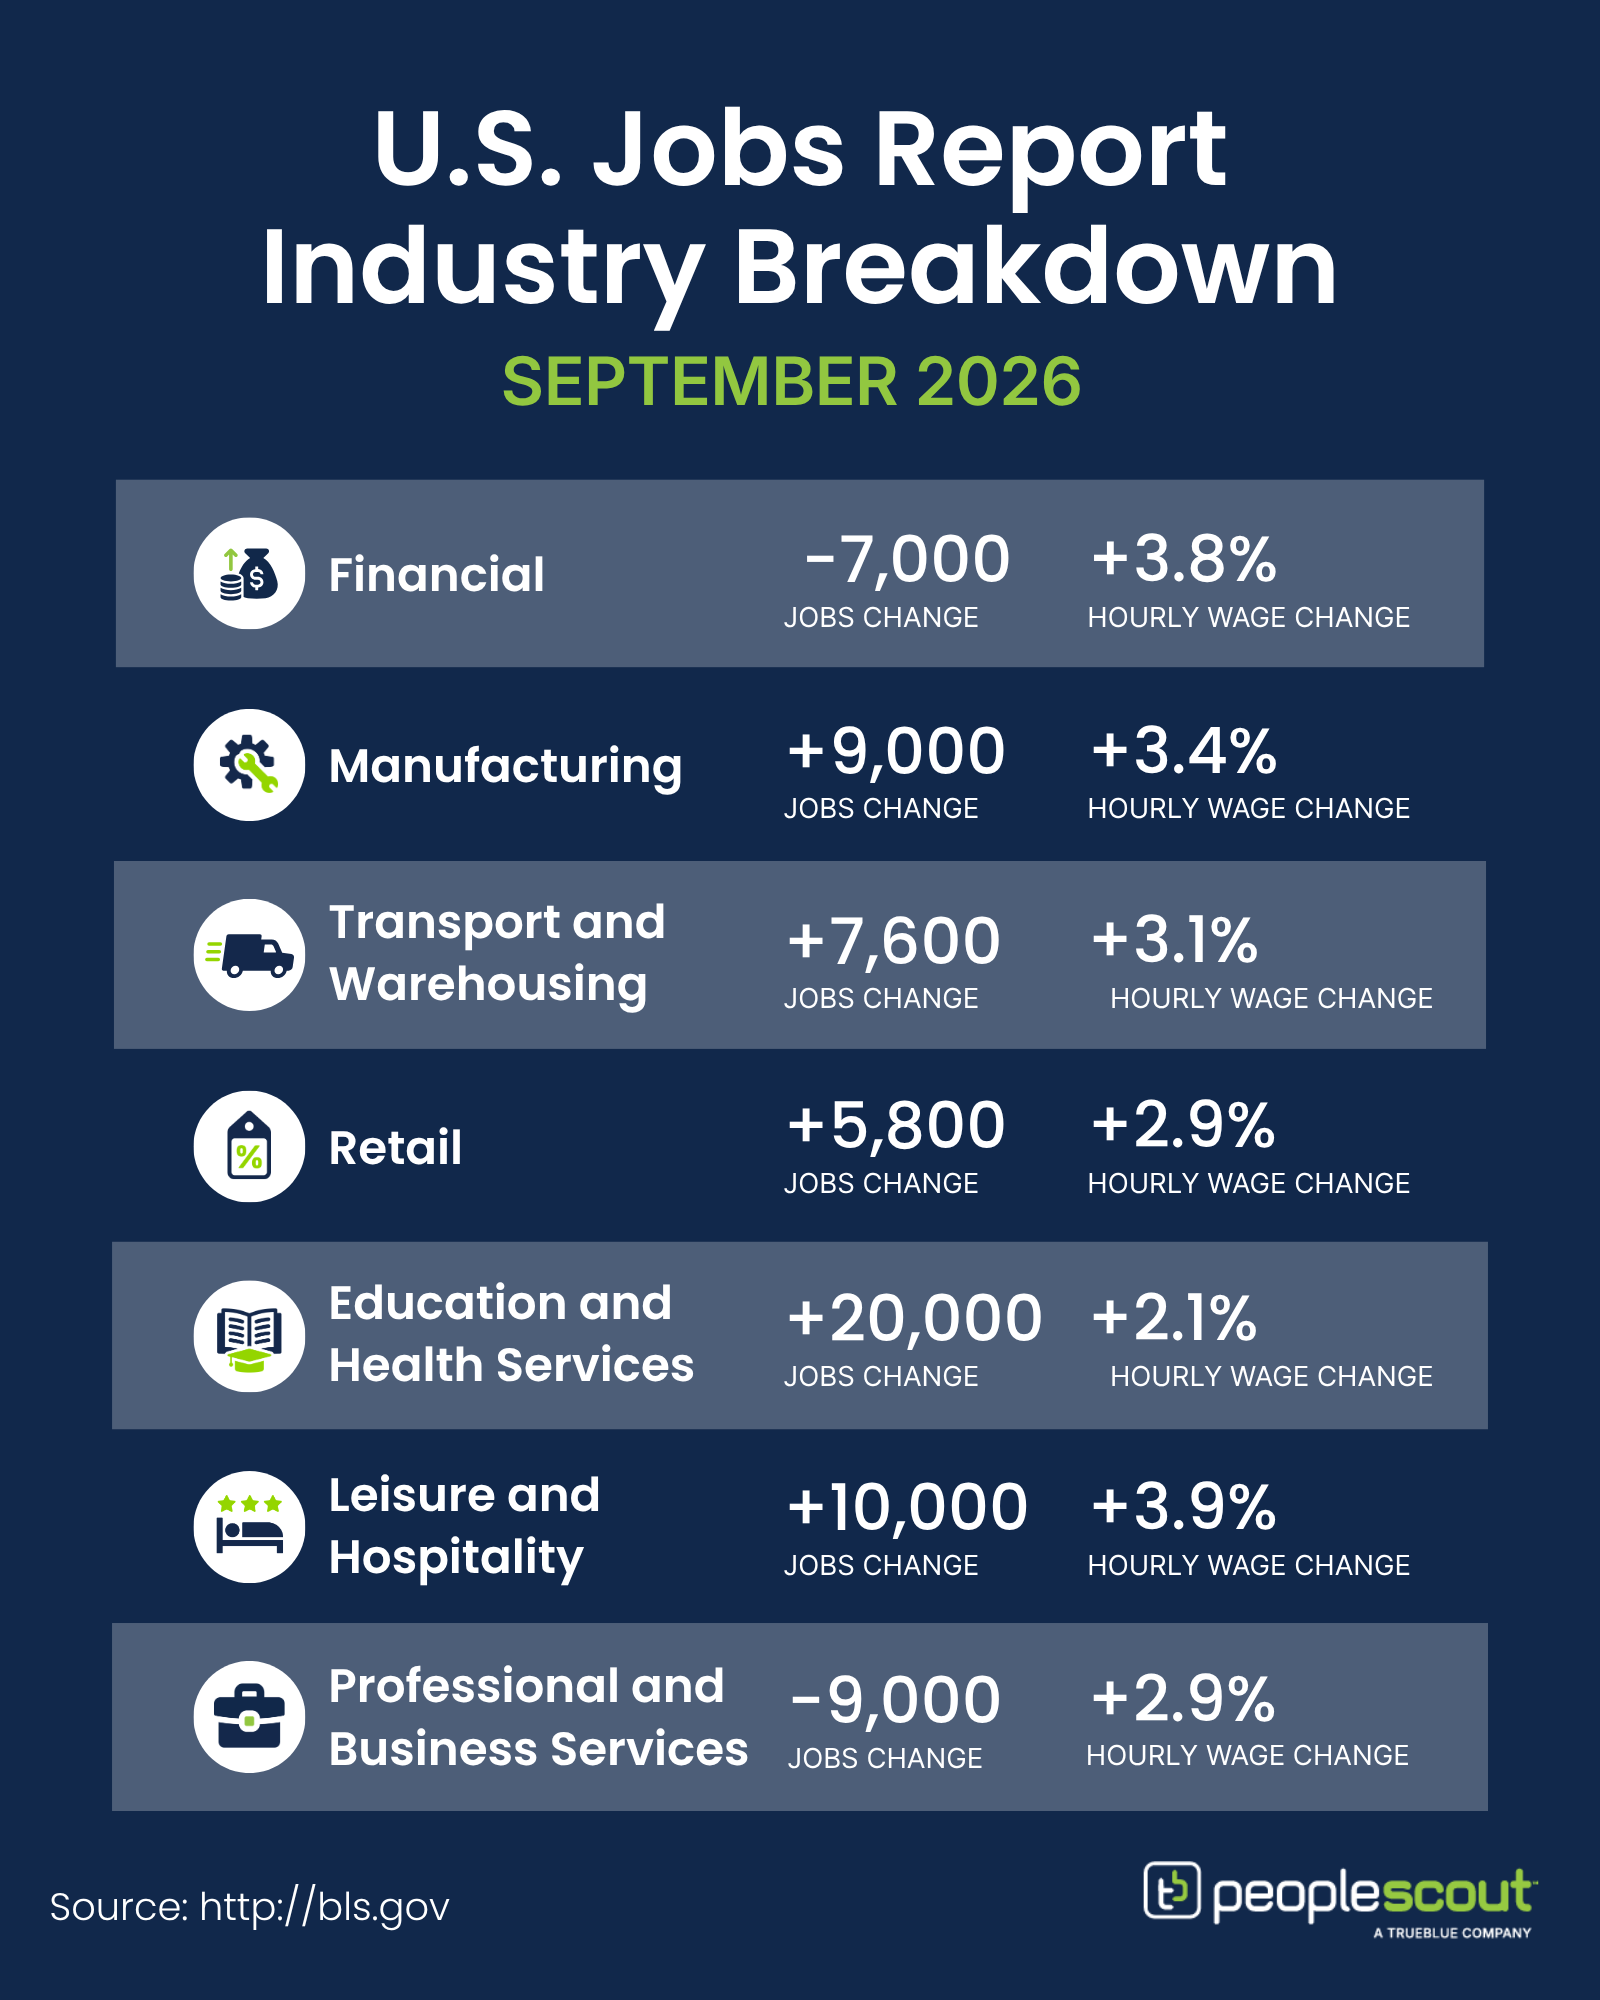
Employers may be hiring more selectively, but they aren’t broadly cutting their workforces. Healthcare added 16,700 jobs, Construction added 11,000, and Leisure and Hospitality gained 10,000. Manufacturing is now up 72,000 jobs since December 2025, providing another sign of gradual improvement in a sector that has faced prolonged hiring pressure. But perhaps more telling is what’s happening outside the payroll number. Initial jobless claims fell to 197,000, employer layoff announcements reached their lowest September level since 2022, and the employment rate among workers ages 25 to 54 rebounded after dipping over the summer. Recent claims data remain near historic lows, reinforcing the picture of employers largely holding onto the people they already have. For talent leaders, that creates an important distinction: slower hiring doesn’t necessarily mean easier hiring. When workers are staying put, employers recruiting skilled trades, clinical, production and other critical talent may still find experienced candidates difficult to dislodge. 

The bad 

The 29,000 jobs added in September fell well short of economists’ expectations, but numbers may have been affected by seasonal-adjustment quirks related to the timing of Labor Day, so the one month shouldn’t be read in isolation. But the pace of job creation is losing momentum, and the slowdown isn’t confined to September. Revisions also removed 60,000 jobs from July and August, turning July into a 10,000-job decline and bringing the three-month average to roughly 51,000. The slowdown is also uneven; some sectors saw growth, while Information lost 10,000 jobs, Professional and Business Services lost 9,000, and Financial Activities lost 7,000. For talent leaders, the takeaway isn’t simply that hiring is declining. Demand is becoming more selective. Employers appear to be scrutinizing where additional headcount creates the most value while continuing to invest in areas where skills remain scarce. That puts greater emphasis on workforce planning: understanding which capabilities should be built internally, where external hiring remains essential, and where more flexible talent models make sense. 

The unknown 

The bigger question is whether today’s slower hiring becomes the new normal—or gives way to another shift in demand. Inflation and interest rates remain important variables. Energy costs have added new price pressure, while recent inflation and employment data have reduced market expectations for another Federal Reserve rate increase in October. A further increase later this year remains possible, making the October 14 Consumer Price Index report another important signal for employers. Labor supply is changing too. Retirements and slower labor-force growth mean the economy may not need to create as many jobs each month as it once did to keep unemployment relatively stable. That makes today’s modest payroll gains harder to interpret using pre-pandemic benchmarks alone. For talent leaders, flexibility may matter more than forecasting the next turn perfectly. Organizations that identify critical skills early, maintain access to flexible recruiting capacity and distinguish between short-term demand changes and longer-term capability needs will be better positioned to adjust as conditions evolve. 

Conclusion 

September’s report reinforces an increasingly important distinction: a slower labor market isn’t necessarily a loose labor market. Employers are adding fewer jobs, but they also aren’t shedding workers at scale. Unemployment remains relatively contained, layoffs are low, and hiring demand continues in sectors where critical skills were already difficult to find. For talent leaders, that means the months ahead may be less about responding to broad labor-market trends and more about understanding the dynamics of their specific talent segments. Balancing cost discipline with the ability to secure, retain and quickly scale critical skills will remain central to workforce strategy. 

PeopleScout Jobs Report Analysis – August 2026

August’s jobs report offers a more encouraging read on a labor market that had been losing momentum over the summer. U.S. employers added 162,000 jobs, nearly triple forecasts, while June and July were revised up by a combined 55,000. The unemployment rate held at 4.1%, even as more workers entered the labor force, while wages grew 3.1% year over year.

The numbers

  • 162,000: U.S. employers added 162,000 jobs in August.
  • 4.1%: The unemployment rate held steady at 4.1%.
  • 3.1%: Wages increased 3.1% over the past year.

The good

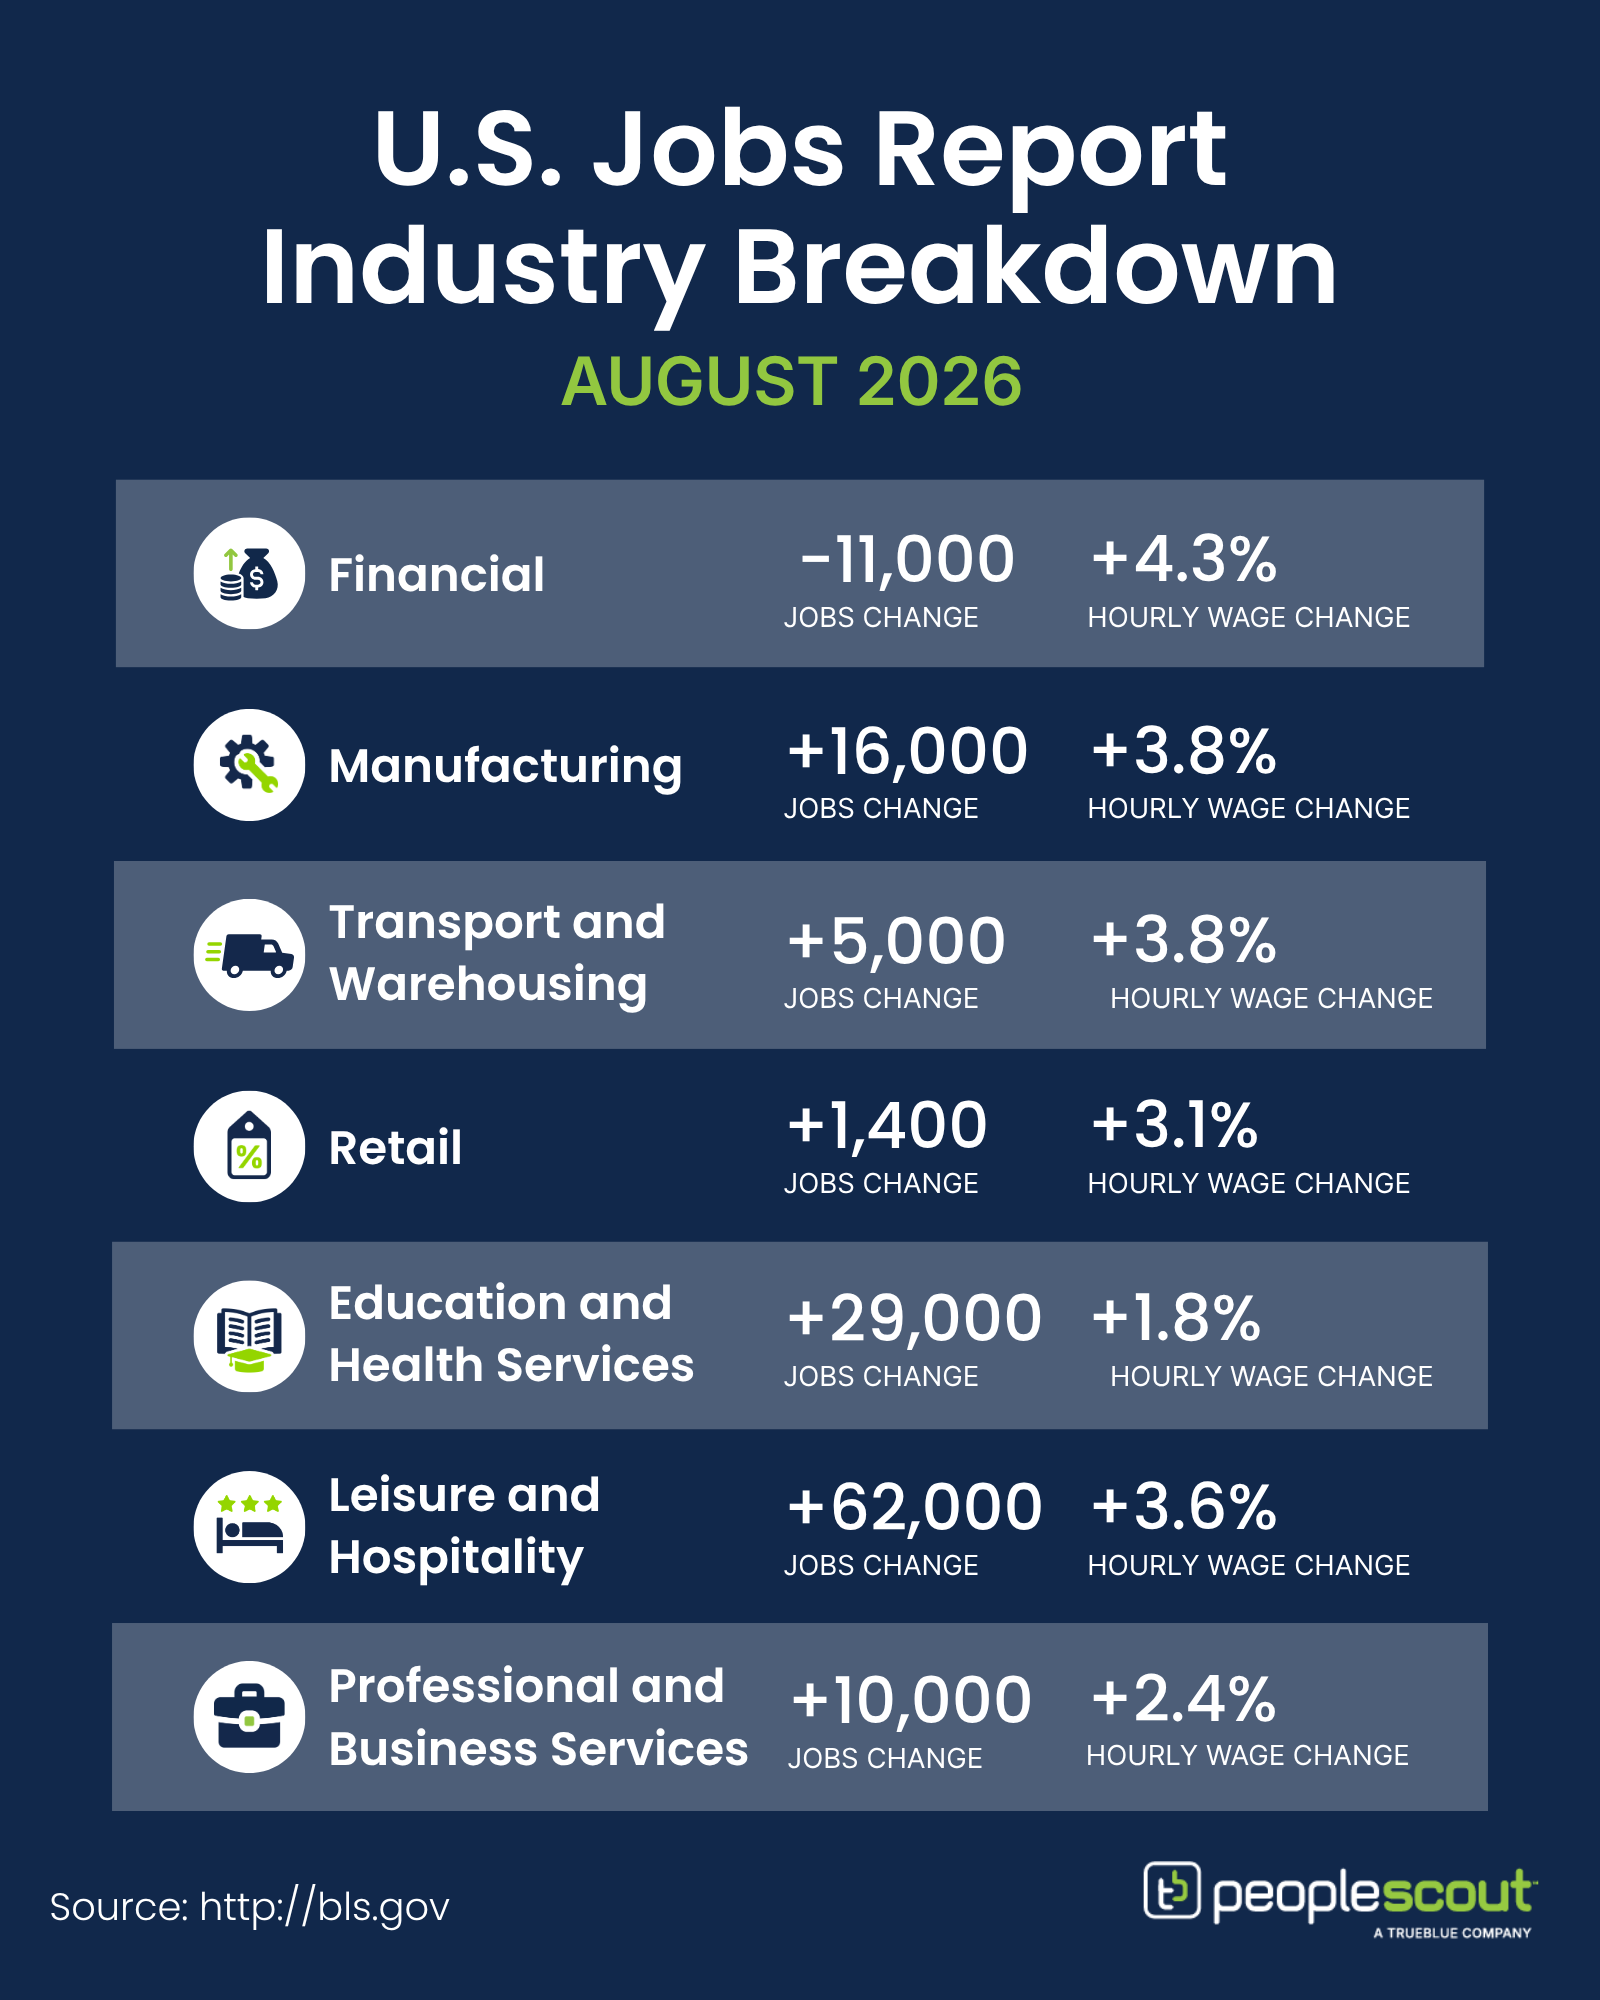
August offered a more encouraging signal for the labor market, with employers adding 162,000 jobs—nearly triple expectations—while the unemployment rate held steady at 4.1%. Upward revisions to June and July added another 55,000 jobs, suggesting the summer slowdown may not have been as pronounced as initially reported. Labor force participation also increased to 61.6%, while the broader measure of unemployment fell to 7.7%, its lowest level since June 2025. Hiring was also more broad-based than in recent months. Leisure and Hospitality led with 62,000 new jobs, including 59,000 in restaurants and bars. Notable gains were also seen in Education and Health Services (29,000), Manufacturing (16,000), and Professional and Business Services (10,000). Layoffs also remain historically low, reinforcing a picture of a labor market that is stable rather than contracting.

For talent leaders, the combination of stronger hiring, low layoffs and a growing labor force suggests employers have some room to move forward on hiring where business demand is clear. Competition for frontline and other in-demand talent is likely to remain elevated, making retention and speed-to-hire important even as broader hiring conditions remain measured.

The bad

Not every sector shared in the month’s momentum. More than 60% of the month’s job gains came from Leisure and Hospitality and local government education, while healthcare—one of the most consistent sources of job growth over the past year—added just 13,000 jobs, well below its prior 12-month average of 32,000. Wage growth continued to cool, with average hourly earnings up 3.1% year over year—the slowest pace since the pandemic-era slowdown and below the current rate of inflation. Meanwhile, job openings and hiring activity have remained relatively flat, suggesting workers may have fewer opportunities to move even as layoffs remain low.

For talent leaders, the unevenness across sectors reinforces the need to resist a one-size-fits-all approach. While some organizations may be positioned to pursue growth, others will remain focused on targeted hiring, productivity and cost management. Understanding where talent demand is building will be more important than reacting to the headline job number.

The unknown

Inflation and Fed policy remain the biggest swing factor. Annual inflation has climbed from 2.4% in February to roughly 3.4% in July, and the stronger jobs report has increased expectations that the Fed could raise rates at its September meeting. Upcoming inflation data will help determine whether the central bank views the strength of the labor market as compatible with its efforts to bring inflation back toward its 2% target. Labor supply is another variable to watch. An aging workforce and slower growth in immigration continue to constrain the pool of available workers, even as demand for labor varies significantly by industry and role.

For talent leaders, the uncertainty reinforces the value of agility. Maintaining flexible workforce plans and being prepared to adjust hiring priorities as economic conditions evolve may be more valuable than committing too early to either expansion or contraction.

Conclusion

The August jobs report provides a more resilient picture of the labor market than the summer’s weakest data suggested, but it is not a clear signal that broad hiring momentum has returned. Stronger-than-expected job growth, upward revisions and low layoffs point to stability, while uneven sector performance, cooling wages and relatively flat hiring activity suggest employers remain selective.

For talent leaders, the takeaway is less about accelerating or slowing hiring across the board and more about knowing where to act. Organizations that can identify the roles and capabilities most critical to business performance—and move quickly when demand emerges—will be better positioned to take advantage of a labor market that appears steadier, but remains highly selective.

PeopleScout Jobs Report Analysis – July 2026

The July 2026 jobs report signals a shift in the U.S. labor market. After several months of modest job growth, employers cut 23,000 jobs in July, falling short of expectations for continued gains. The unemployment rate edged down to 4.1%, but the decline came alongside a further drop in labor force participation, which fell to 61.4%. Wage growth also cooled to 3.2% year over year, its slowest pace in recent months. Combined with significant downward revisions to May and June payrolls, the latest data suggests the labor market is cooling more than recent reports had indicated — though pockets of continued demand and historically low layoffs point to a more nuanced picture.

The Numbers

  • -23,000: U.S. employers cut 23,000 jobs in July.
  • 4.1%: The unemployment rate ticked down to 4.1%.
  • 3.2%: Wages increased 3.2% over the past year.

The Good

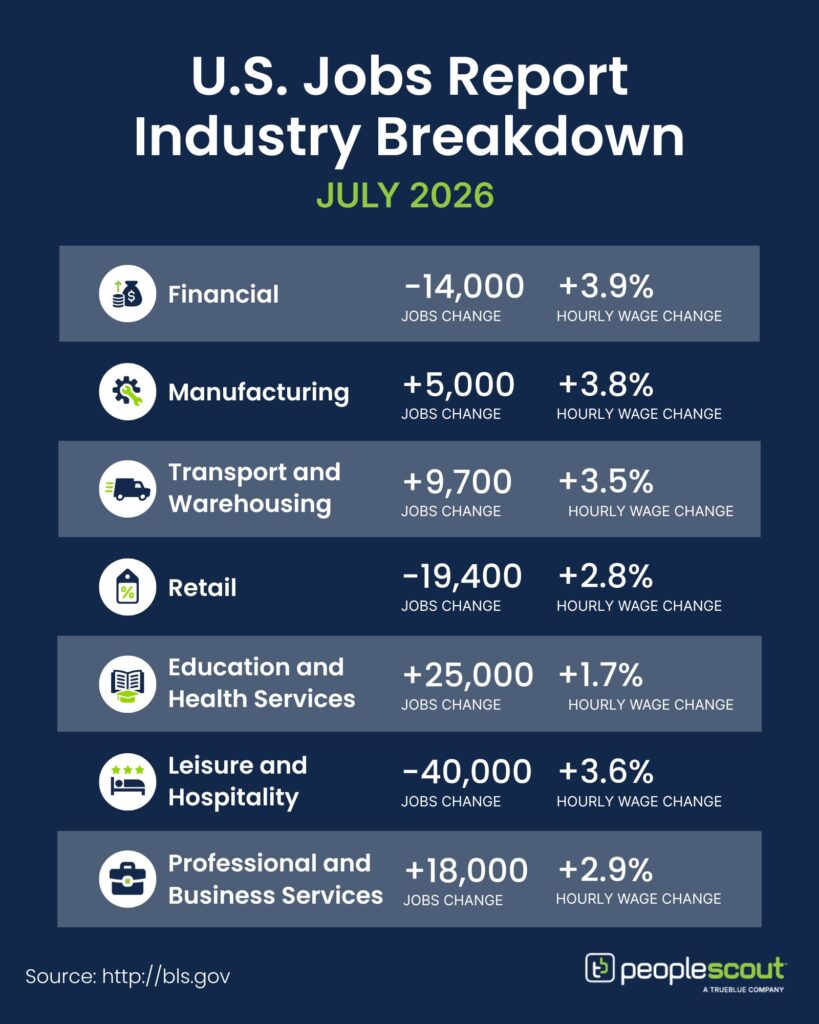
Despite the weak headline, several sectors continued to add jobs and layoffs remained historically low. Education and Health Services led with 25,000 new jobs, supported by continued gains in healthcare and social assistance Professional and Business Services added 18,000 jobs, while manufacturing (+5,000) and construction (+22,000) also posted gains, offering early signs of stabilization in goods-producing industries. At the same time, outplacement data show announced layoffs falling to a two-year low in July, while job openings and quit rates appear to have stabilized, even if they have not yet turned meaningfully upward.

For talent leaders, continued hiring in healthcare and professional services — combined with historically low layoff volumes — suggests competition for experienced talent in critical roles may persist even as overall hiring cools. Retaining key talent remains just as important as bringing new talent into the organization.

The Bad

The July data provides a clearer signal that hiring momentum is weakening. Government payrolls fell by 53,000 jobs, driven largely by a 50,000-job decline in local government education. Leisure and Hospitality lost another 40,000 jobs following a 61,000-job decline in June, while retail (-19,400) and Financial Activities (-14,000) also contracted. Wage growth slowed to 3.2%, and labor force participation fell again to 61.4% as several hundred thousand people exited the labor force.

For talent leaders, these declines reinforce the need for a selective approach to workforce investment. Rather than responding with broad-based hiring freezes or continued expansion, organizations may benefit from focusing hiring on the roles and capabilities most critical to business performance — while managing costs and preserving flexibility elsewhere.

The Unknown

Several factors will shape the labor market outlook through the remainder of the year. Elevated costs tied to disrupted oil shipments and renewed tariff actions continue to work through the economy, and it remains unclear how significantly they will affect hiring and consumer spending. The Federal Reserve held rates steady at its most recent meeting and will have another jobs report, along with additional inflation data, to consider before its September decision.

The labor supply picture also remains uncertain. Participation among prime-working-age adults partially rebounded in July following a sharp decline in June, while a slower pace of immigration continues to constrain the growth of the available workforce. That dynamic could create tighter labor supply in some industries even as overall hiring slows.

For talent leaders, the uncertainty reinforces the value of agility. Successful organizations will be those that can adjust hiring priorities, workforce plans and talent investments as conditions change.

Conclusion

The July jobs report points to a labor market that is cooling more than previously understood, but the picture is not uniformly negative. For talent leaders, the takeaway is less about choosing between “hire” and “freeze” and more about being intentional about where to invest. Protecting critical talent, focusing hiring on high-value roles and maintaining the flexibility to adjust workforce plans will be increasingly important as employers navigate a labor market that remains difficult to predict.

Q2 2026 U.S. Labor Market Insights: The Quiet Slowdown and the AI Efficiency Divide 

The U.S. labor market closed Q2 2026 with hiring momentum slowing, but without the sharp deterioration many had anticipated. April and May delivered stronger-than-expected payroll figures before hiring declined in June, with just 57,000 new jobs added — the softest month of the quarter and well below the threshold most economists consider healthy growth. Yet unemployment edged down to 4.2%, and wage growth remained relatively steady, reflecting a labor market that continues to show resilience even as underlying dynamics shift.  

The defining story of Q2 was not whether the labor market was growing or slowing, but the widening gap between headline stability and increasingly uneven conditions across industries.  

Q2 2026 By the Numbers 

  • Unemployment: Q2 ended with the unemployment rate at 4.2%, edging down from 4.3% where it had held for most of the quarter. However, the decline was accompanied by a lower labor force participation rate, indicating that the improvement is not entirely driven by hiring activity. 
  • Job Creation: Payroll growth followed an unpredictable path. April came in at 115,000 jobs before being revised upward to 179,000 gains. May delivered 172,000, followed by a significant drop to just 57,000 new jobs in June. Revisions to both April and May in the June report resulted in a net decrease of 74,000 jobs, tempering Q2’s overall growth picture. 
  • Wage Growth: Annual wage growth fluctuated within a narrow band throughout the quarter—3.6% in April, falling to 3.4% in May (its lowest level since 2021) before recovering slightly to 3.5% in June. 
  • Job Openings: After recovering to 7.15 million at the end of Q1 2026, openings rose to 7.6 million in April and held there through May — well above market expectations and the highest level since mid-2024. 
  • Sector Standouts: Education and Health Services sustained the market across all three months. Professional and Business Services returned to growth in June (+36,000). Financial Activities recorded losses in April and May before going flat in June. Leisure and Hospitality swung sharply, surging in May (+70,000) before shedding 61,000 in June. 

Top 4 Trends Shaping Q2 2026 

1. The Market’s Mixed Signals 

Q2’s central paradox was the disconnect between what the data showed and how business leaders felt about it. Unemployment fell, wages held steady and the economy continued to grow—yet CEO confidence fell from 59 in Q1 to 47 in Q2, tipping into negative territory for the first time this year, according to The Conference Board Measure of CEO Confidence™ survey. Nearly half of CEOs reported that economic conditions had worsened over the prior six months, and 40% expected further deterioration ahead. Hiring intent softened in parallel—31% of CEOs anticipated reducing their workforce over the next 12 months, up from 27% in Q1, while only 28% expected to add headcount. 

The jobs data reflects some of that caution. June’s 57,000 payroll gain was the weakest of the quarter, revisions reduced hiring totals for earlier months, and the decline in unemployment came alongside declining labor force participation, underscoring that the headline figures tell only part of the story. The market is not deteriorating, but the gap between what the numbers show and how employers are responding appears to be widening. 

2. The Load-Bearing Role of Healthcare in a Slowing Market 

If Q2 had a single structural constant, it was the outsized contribution of Education and Health Services to overall job creation. Healthcare added 37,000 jobs in April and 35,000 in May, while the broader Education and Health Services sector added 69,000 in June, balancing net job gains as other industries declined. Without this sector, Q2’s employment picture would have looked considerably weaker. 

The drivers behind this sustained demand show no sign of easing: an aging population, persistent shortages of clinical and allied health professionals, and roles that depend on human interaction, clinical judgment and physical dexterity. While other sectors are evaluating whether technology can absorb capacity, healthcare continues to rely heavily on people.

3. The AI Efficiency Overhang  

The impact of AI on employment is not arriving as a sudden wave of displacement, but rather as a quiet, selective reconfiguration of where and whether headcount gets added. Financial Activities recorded losses in both April and May before flattening in June. Information services shed positions in April. Major employers including HSBC and Mizuho have signaled longer-term reductions in administrative roles, typically framed as reallocation toward higher-value work. A survey of 750 CFOs projected a modest but uneven 0.4% net headcount decline across 2026, with the burden falling disproportionately on office support functions. 

The JOLTS data adds a further dimension. April’s surge in job openings was concentrated almost entirely in Professional and Business Services (+668,000), yet actual hiring in the sector (+7,000 jobs) remained subdued. Openings are staying on the books longer not because demand is booming, but because workers are not moving. The quits rate, at 1.9%, sits well below its pre-pandemic range, reflecting a workforce that feels it has fewer options. The result is a market that looks active on the surface but is experiencing considerably less actual movement than the headline openings figure implies. 

4. The Hidden Cost of Wage Cooling 

On the surface, Q2’s wage trajectory looked stable—annual growth held within a narrow 3.4–3.6% band throughout the quarter. But wage growth continuing to trail inflation means many workers’ earnings are not keeping pace with the cost of living, and sentiment data reflects that reality. Just 28% of Americans believed it was a good time to find a quality job, down from 70% in mid-2022, with college graduates particularly pessimistic at just 19%. The subdued quits rate reinforces the picture—workers are staying put, but out of caution rather than satisfaction. 

Against this backdrop, the U.S. gender pay gap widened for the second consecutive year, with women now earning 81 cents for every dollar earned by men—the first back-to-back increase since the 1960s. The combination of stagnant real wages, declining worker confidence and widening pay gap is creating employee experience conditions that will increasingly test retention strategies. 

What This Means for TA Leaders 

Q2 delivered a market that held together without accelerating, and talent strategies must operate in the gap between stability and growth 

Anchor hiring decisions in business outcomes, not market momentum. Lower CEO confidence means headcount decisions will face greater scrutiny from leadership. TA teams that can quantify the ROI of specific hires—rather than pointing to market conditions as justification—will carry more weight in H2 planning conversations. 

Healthcare and specialist talent competition has no near-term ceiling. The sector that sustained Q2’s employment picture faces the same structural shortages it did entering the quarter. For any organization dependent on clinical, allied health or care-facing roles, proactive pipelines, internal mobility pathways and education partnerships are becoming prerequisites rather than differentiators. 

Audit which open roles are being filled. The AI efficiency overhang isn’t showing up as layoffs—it’s showing up as headcount held open and job functions quietly redesigned. Knowing which vacancies reflect genuine demand versus roles being absorbed by productivity tools is increasingly a core workforce planning competency, not a nice-to-have. 

Treat declining sentiment as a leading retention indicator. Wage growth trailing inflation, worker pessimismand a widening gender pay gap don’t generate visible attrition spikes immediately—but they erode engagement over time. Total rewards transparency, equitable pay practices and meaningful career development conversations are retention strategies now, not value commitments for better conditions later. 

Q2 delivered a labor market that is slowing without breaking. For talent leaders, the strategic response is not to wait for clarity—it is to build workforce precision, pipeline depth and organizational agility to perform effectively for whatever lies ahead. 

PeopleScout Jobs Report Analysis – June 2026

The June 2026 jobs report points to a labor market that continues to expand, though at a slower pace than earlier this year. U.S. employers added 57,000 jobs, reflecting more measured hiring after stronger gains in recent months, even with payroll estimates for both April and May revised downward by a combined 74,000. The unemployment rate edged down to 4.2%, although the decline occurred alongside a lower labor force participation rate, suggesting the improvement reflects more than hiring activity alone. Annual wage growth held at a healthy 3.5%. June’s report reinforces the picture of a labor market that is gradually moderating rather than weakening.

The Numbers 

  • 57,000: U.S. employers added 57,000 jobs in June. 
  • 4.2%: The unemployment rate declined to 4.2%. 
  • 3.5%: Wages increased 3.5% over the past year. 

The Good 

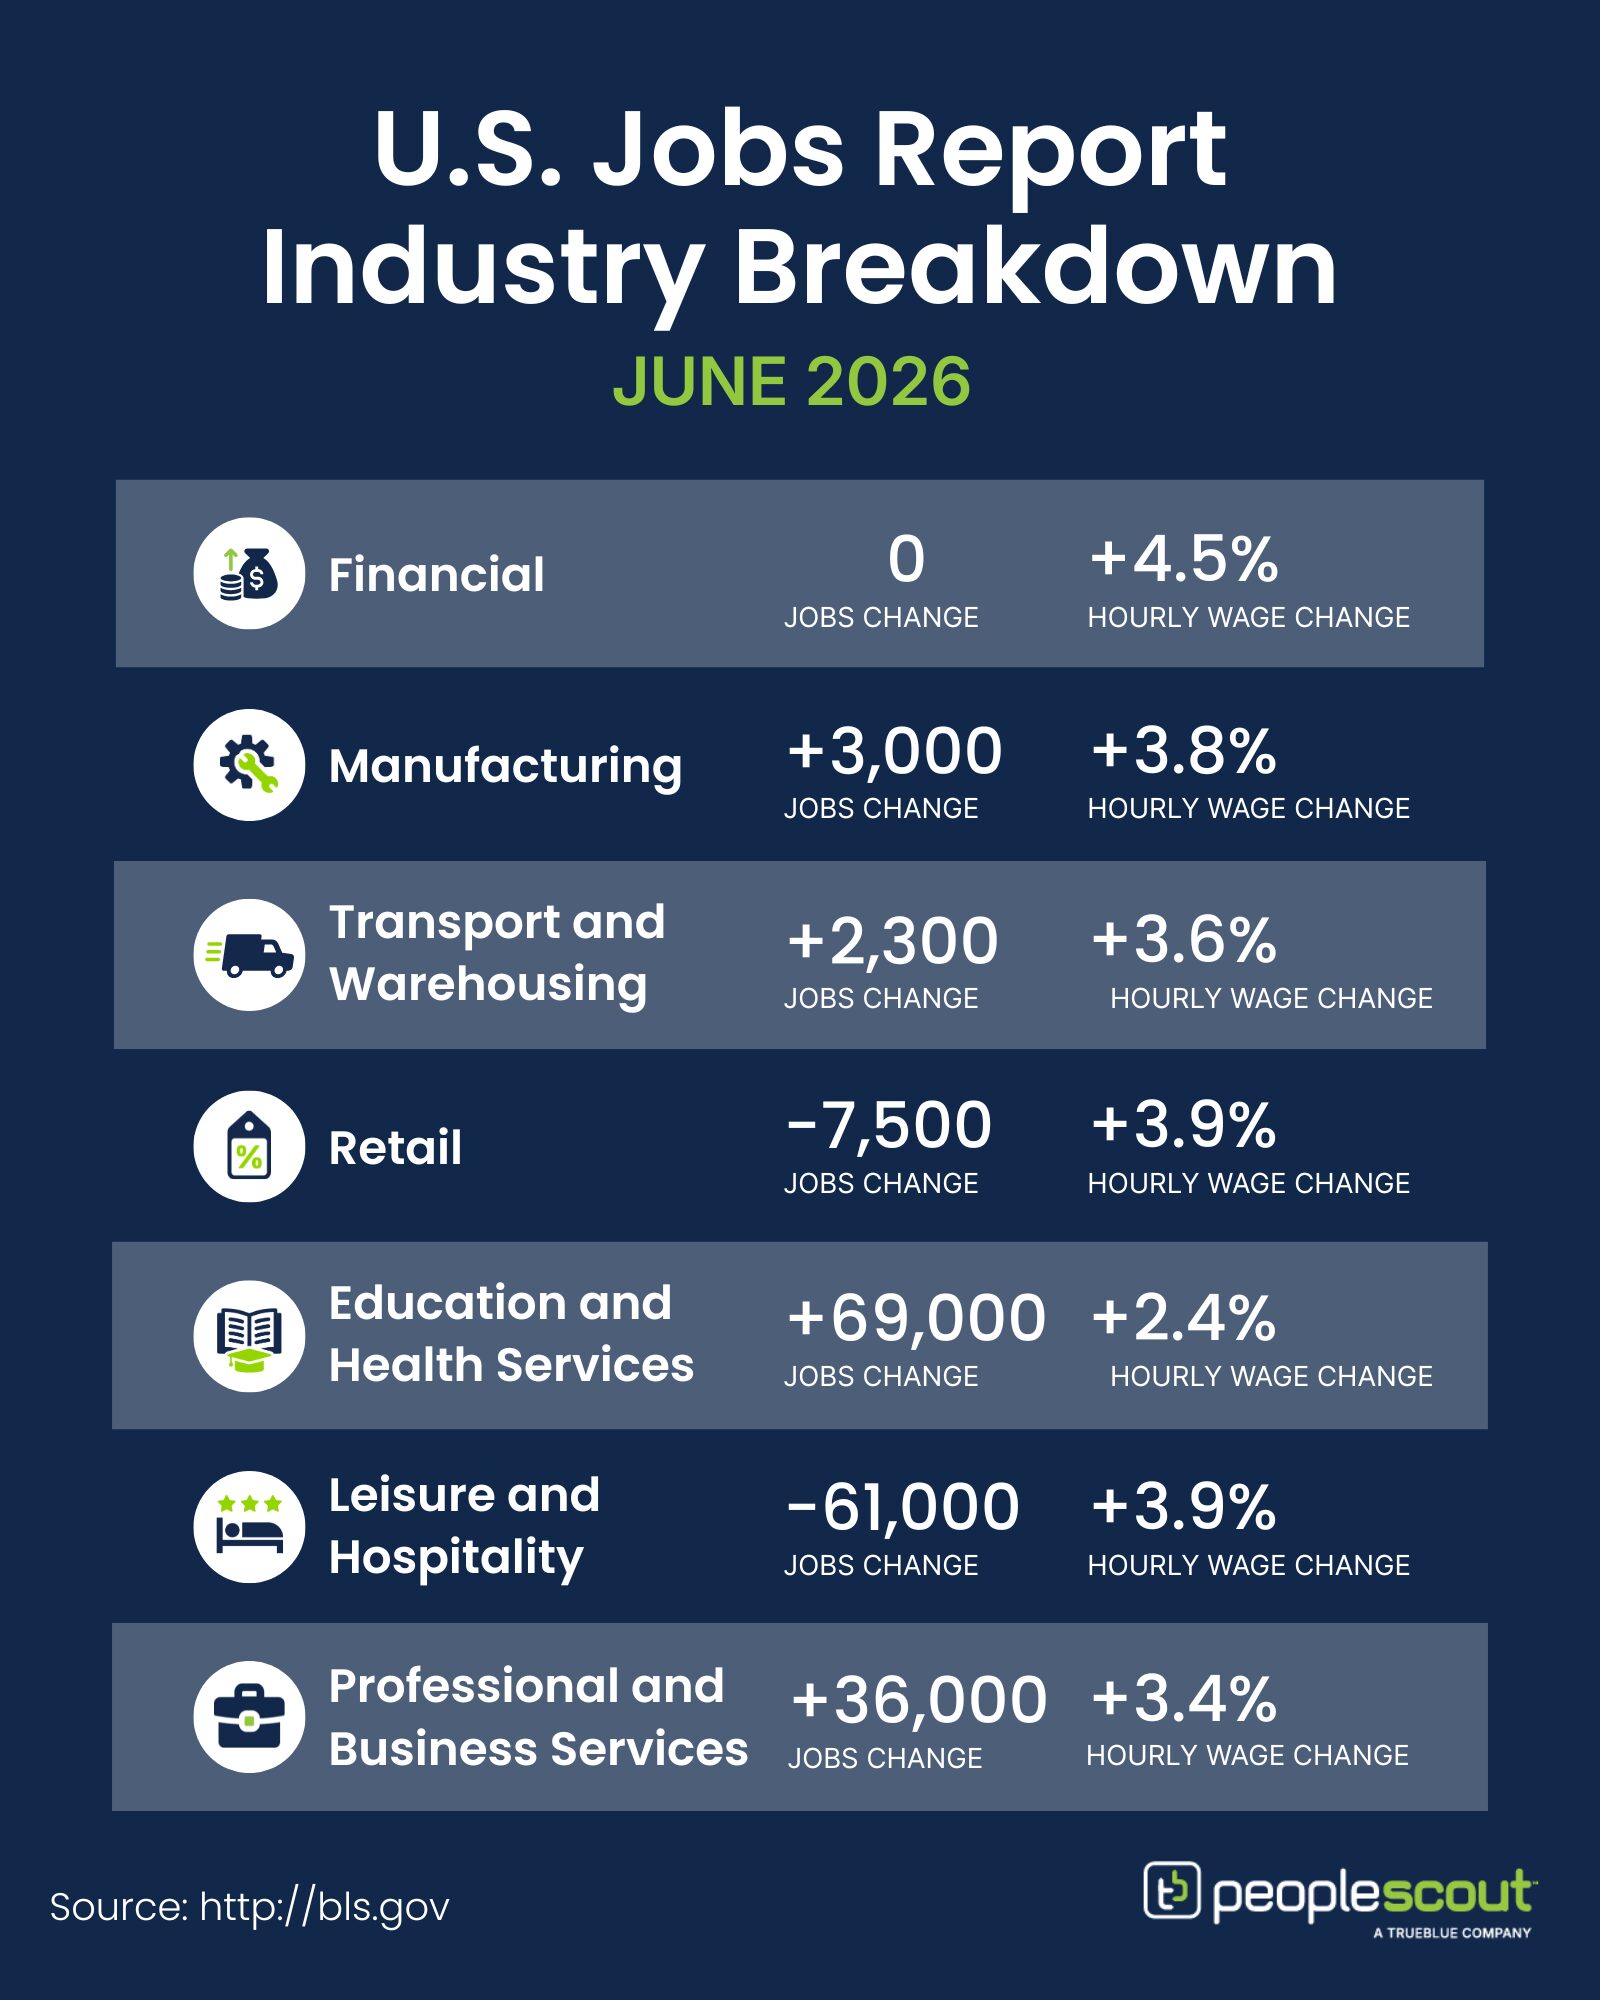
Several sectors continued to demonstrate resilience despite slower overall hiring. Education and Health Services led job growth with 69,000 jobs, although healthcare hiring continued at a slower pace than its recent average. Professional and Business Services added 36,000 jobs, signaling continued demand for specialized talent and business support functions. Transportation and Warehousing also posted modest gains. At the same time, unemployment edged lower and wage growth remained steady, suggesting employers are continuing to invest in talent where business needs remain strong. For talent leaders, competition for healthcare professionals, skilled specialists and critical business functions is likely to remain elevated, reinforcing the value of proactive talent pipelines and targeted recruitment strategies. 

The Bad 

Overall hiring slowed considerably in June, with payroll growth falling well below the pace seen earlier this spring. Job losses were concentrated in Leisure and Hospitality, which shed 61,000 positions, while Retail also declined. Manufacturing hiring remained positive but modest, and Financial Activities was flat. These mixed results suggest that many organizations are hiring selectively while carefully managing labor costs and evaluating demand. Rather than broad-based expansion, employers appear to be prioritizing investments in the functions and skills most closely aligned with business objectives. 

The Unknown 

While labor market fundamentals remain relatively healthy, employers continue to navigate persistent cost pressures, evolving consumer demand and an uncertain economic outlook. At the same time, continued investment in automation and AI is influencing how organizations think about workforce planning and productivity, even as demand for specialized skills remains strong. For talent leaders, maintaining flexibility will remain essential. Organizations that continuously monitor labor market conditions, adapt hiring plans and invest in critical capabilities will be better positioned to respond as conditions evolve. 

Conclusion 

Hiring continues across key sectors, unemployment remains low and wage growth is steady, but payroll gains have moderated and industry performance is increasingly uneven. The slower pace of hiring, combined with downward revisions to prior months, suggests organizations are becoming more deliberate in where and how they add talent rather than stepping away from hiring altogether. For talent leaders, success will continue to depend on strategic workforce planning, targeted hiring investments and the agility to adjust recruitment strategies as market conditions change. 

PeopleScout Jobs Report Analysis – May 2026

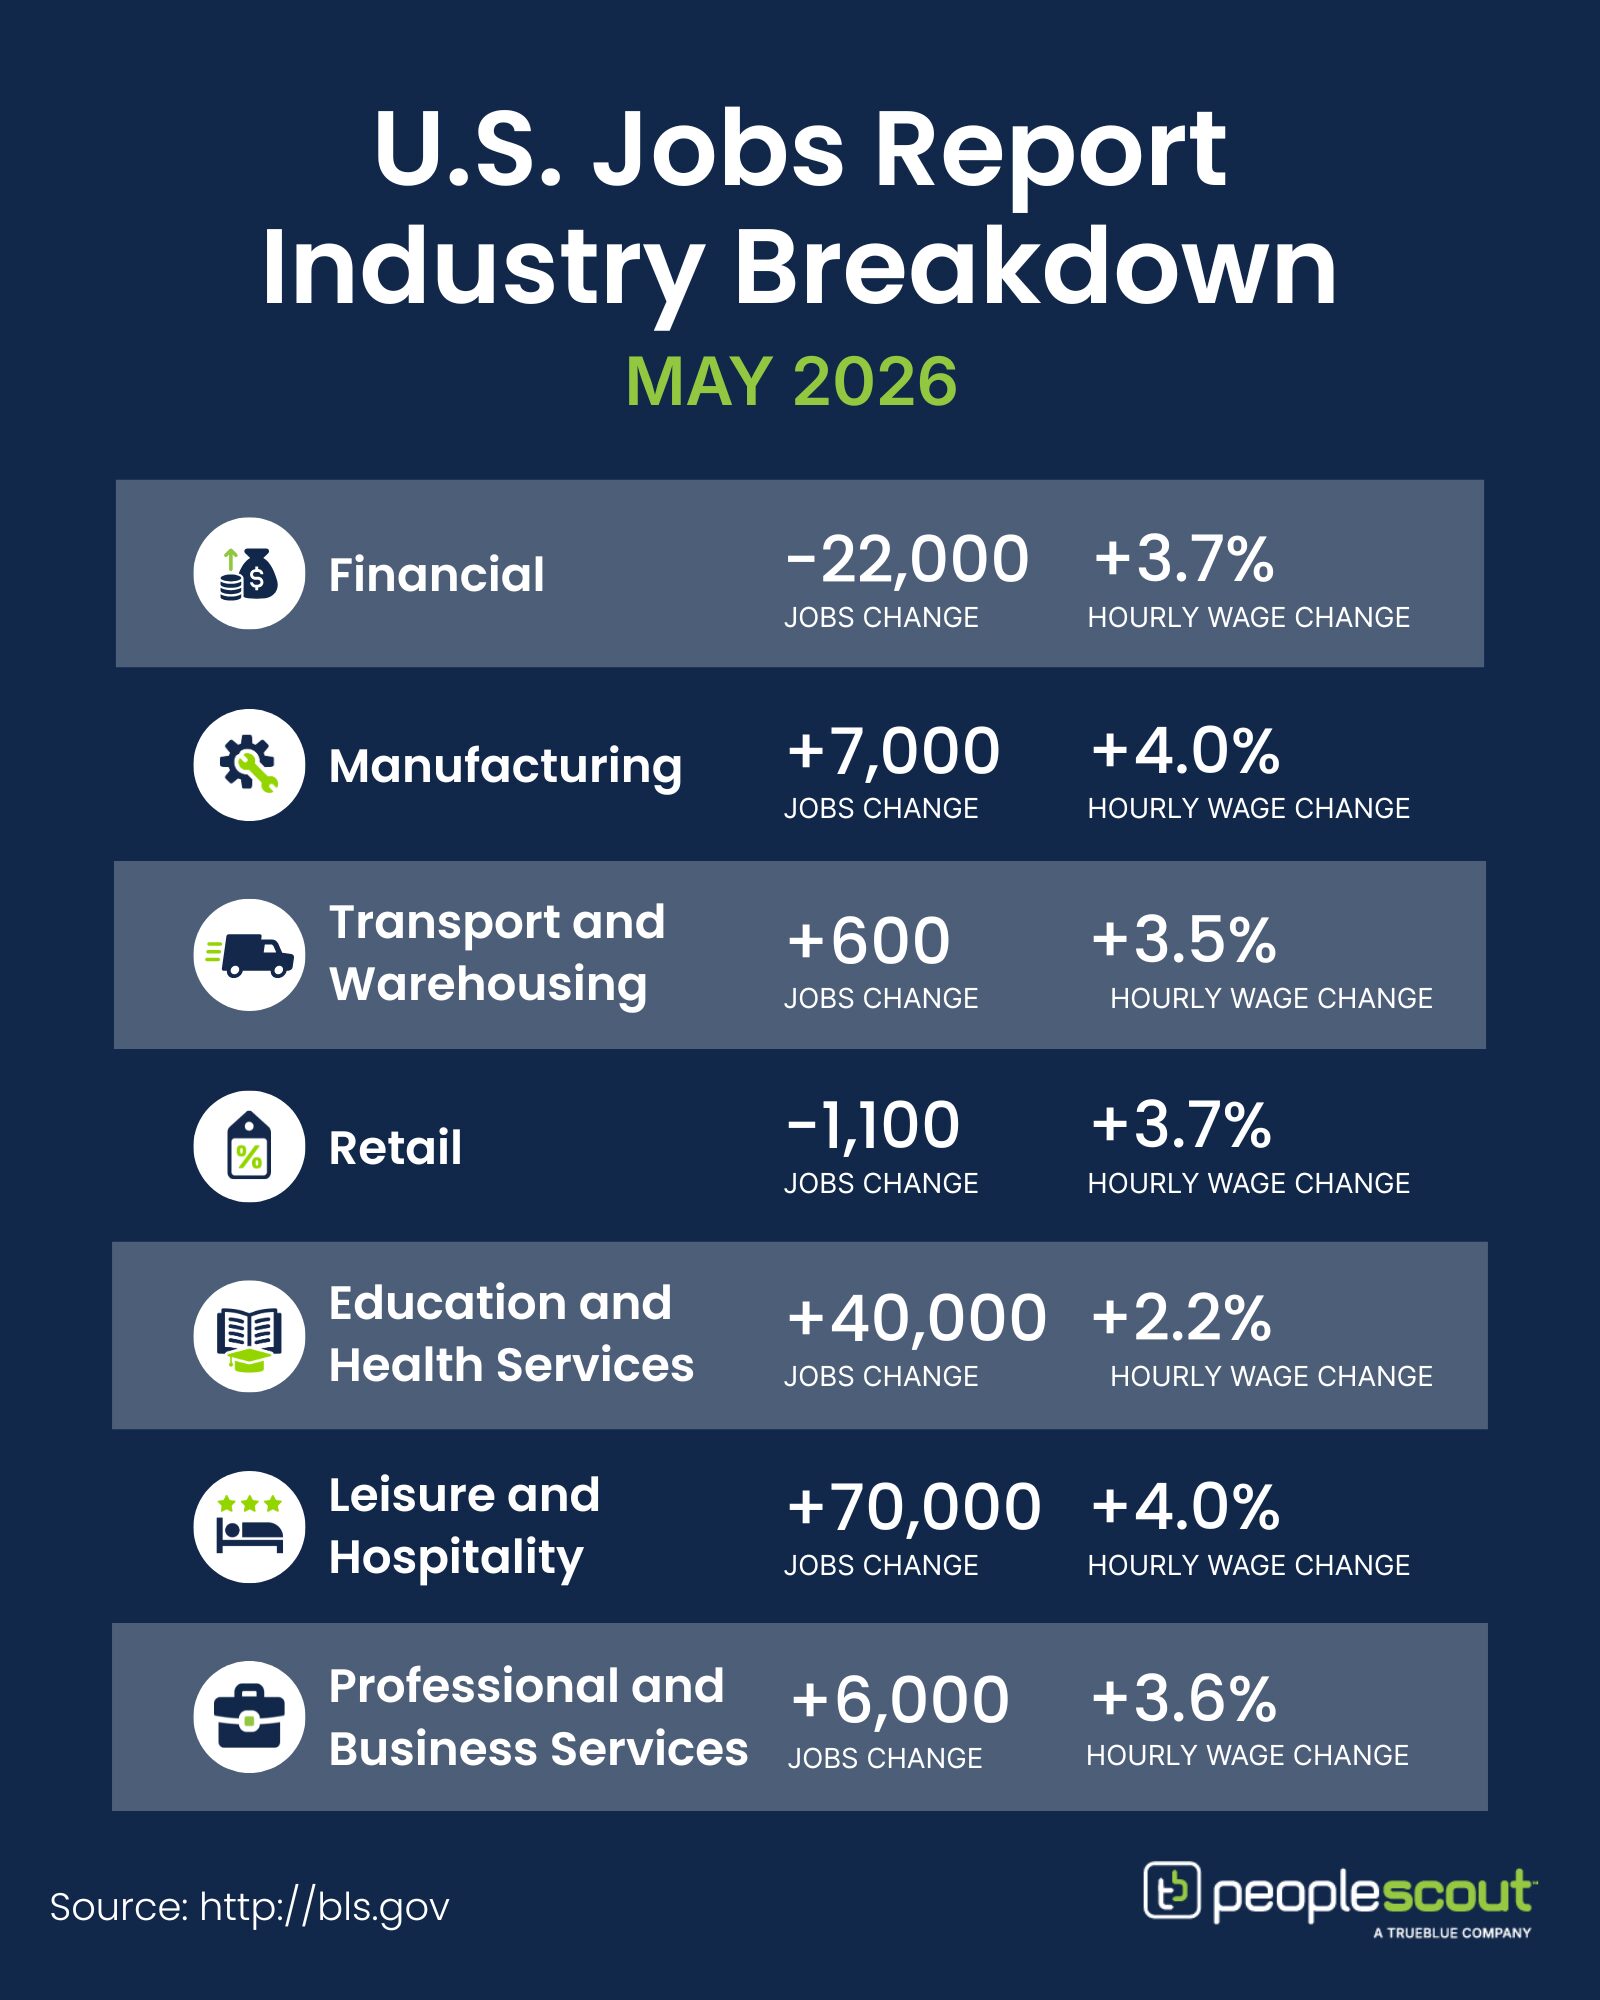
The May 2026 jobs report suggests a labor market that remains steady and resilient despite ongoing economic uncertainty. U.S. employers added 172,000 jobs last month, exceeding expectations and building on stronger-than-reported gains in March and April. The unemployment rate remained unchanged at 4.3%, while annual wage growth slowed to 3.4%, its lowest level since 2021. Hiring broadened across more industries than in recent months, though growth remains concentrated in a handful of sectors. At the same time, wage growth continues to trail inflation, creating additional pressure for both employers and workers.

The Numbers 

  • 172,000: U.S. employers added 172,000 jobs in May. 
  • 4.3%: The unemployment rate remained unchanged. 
  • 3.4%: Wages increased 3.4% over the past year. 

The Good

May’s report was stronger than expected and provides further evidence that the labor market has regained momentum following a sluggish 2025. Hiring was led by Leisure and Hospitality, which added 70,000 jobs, while Healthcare contributed another 35,000 positions. Job growth also became more broadly distributed across industries, and upward revisions to March and April payroll data added another 93,000 jobs, reinforcing the picture of a labor market that remains healthier than many anticipated. For talent leaders, continued job growth and limited layoffs suggest competition for critical talent is likely to persist, particularly in frontline, healthcare and customer-facing roles.

The Bad

While the headline numbers were encouraging, underlying challenges remain. Wage growth slowed to 3.4% year over year and continues to lag inflation, which may affect employee sentiment and retention as workers feel increasing pressure from rising living costs. Sector performance also remains uneven. Financial Activities lost 22,000 jobs in May and Transportation and Warehousing remains below its recent peak despite modest gains. Many employers continue to maintain headcount while carefully evaluating productivity, efficiency and long-term workforce investments. For employers, workforce planning decisions are increasingly focused on targeted hiring rather than broad expansion.

The Unknown

Several economic variables continue to cloud the outlook for the second half of the year. Higher energy and transportation costs are beginning to ripple through the broader economy, contributing to inflationary pressures that may affect both consumer spending and business investment decisions. At the same time, policymakers remain focused on inflation trends, creating uncertainty around the future path of interest rates. While hiring momentum has improved, many organizations are likely to continue balancing growth ambitions against cost management priorities. For talent leaders, flexibility remains critical. Organizations that can adapt hiring strategies quickly, prioritize critical skills and maintain visibility into workforce needs will be better positioned as economic conditions continue to evolve.

Conclusion

The May 2026 jobs report points to a labor market that remains stable and surprisingly resilient. Hiring exceeded expectations, unemployment held steady and job growth broadened across more sectors. However, wage growth continues to moderate, inflation remains a concern and hiring activity is still uneven across industries. Rather than signaling a return to aggressive workforce expansion, the report suggests employers remain focused on measured growth, operational efficiency and targeted talent investments. For talent leaders, success in the months ahead will likely depend on maintaining workforce agility—balancing near-term business needs with long-term talent readiness while continuing to compete for the skills most critical to future growth.

PeopleScout Jobs Report Analysis – April 2026

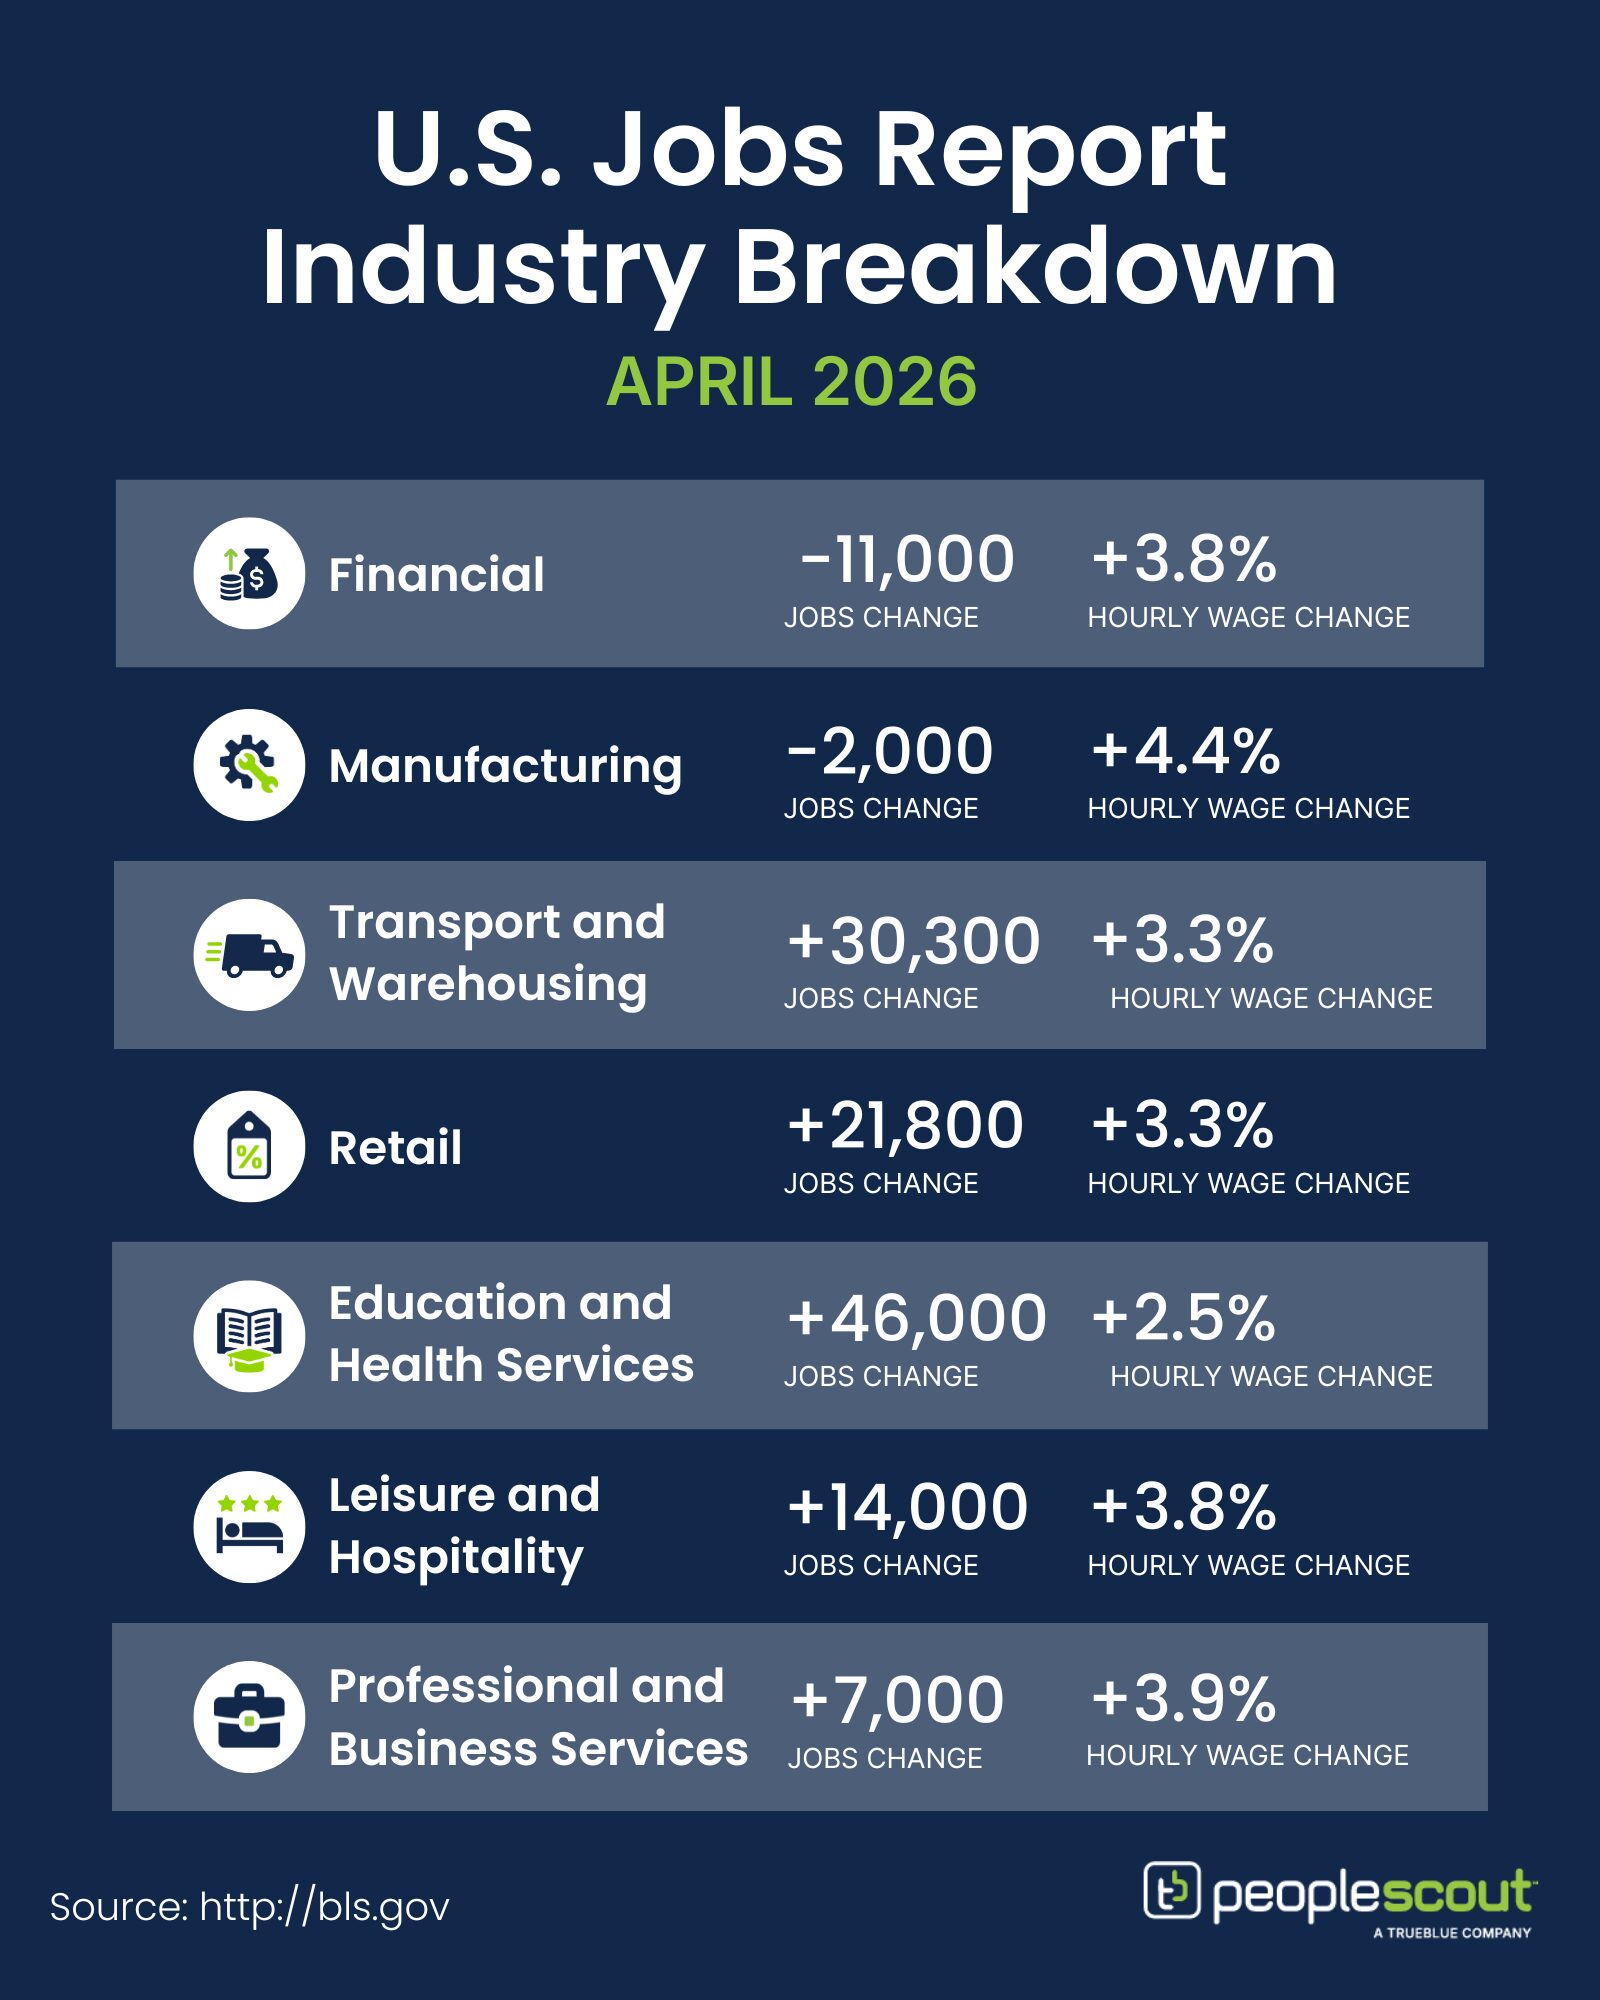
The April 2026 jobs report points to a labor market that remains resilient, but increasingly cautious. U.S. employers added 115,000 jobs last month, outperforming expectations despite ongoing uncertainty tied to higher energy costs and geopolitical tensions in the Middle East. The unemployment rate held steady at 4.3%, while wage growth moderated slightly to 3.6% year over year. Hiring remains concentrated in sectors like healthcare, transportation and retail, while areas including information and financial services continued to lose jobs.

The Numbers 

  • 115,000: U.S. employers added 115,000 jobs in April. 
  • 4.3%: The unemployment rate remained unchanged. 
  • 3.6%: Wages increased 3.6% over the past year. 

The Good 

April’s report exceeded expectations and marks a second consecutive month of positive job growth, reinforcing the labor market’s resilience despite broader uncertainty. Healthcare led hiring again, adding more than 37,000 jobs, while Transportation and Warehousing (+30,000) and Retail (+22,000) also posted gains. Layoffs also remain limited, even as hiring slows. For talent leaders, this continues to support a competitive environment for critical skills and experienced talent. Wage growth also continues to cool gradually, which may provide some relief for organizations balancing hiring needs with cost management objectives.  

The Bad 

Despite the stronger-than-expected headline, the broader labor market remains sluggish by historical standards. Labor force participation declined again in April, while the number of workers employed part-time for economic reasons increased significantly. Sector performance also remains uneven. Information services lost 13,000 jobs, while financial activities declined by 11,000. Employers in technology and corporate functions continue to evaluate efficiency, automation and long-term workforce structure. While AI has not triggered widespread displacement, talent leaders are increasingly reassessing which roles drive the greatest strategic value and where productivity gains may reduce future hiring demand. At the same time, elevated gas prices and persistent inflation continue to pressure both businesses and consumers, which could weigh on hiring activity in the months ahead. 

The Unknown 

Geopolitical uncertainty remains a key variable. While the labor market has so far remained relatively insulated from the economic effects of the Iran conflict, sustained increases in fuel and transportation costs could eventually impact consumer spending, business confidence and hiring activity. Many employers appear to be taking a wait-and-see approach while evaluating how broader economic conditions unfold over the coming months. For talent leaders, this environment reinforces the importance of agility. Hiring strategies built around flexibility, workforce planning and critical-skill prioritization may prove more effective than broad-based expansion strategies in the current market.

Conclusion 

The April 2026 jobs report reinforces a labor market that continues to slow gradually without significantly weakening. Hiring remains positive, unemployment is relatively stable and layoffs are still limited—but growth is increasingly concentrated in select sectors, while employers remain cautious about long-term workforce expansion. Rather than scaling hiring aggressively, many employers are prioritizing operational efficiency, targeted workforce investments and retention of high-value talent. Success in the months ahead may depend on balancing short-term cost pressures with long-term workforce readiness—ensuring organizations remain adaptable while continuing to secure the talent most critical to future growth.

Q1 2026 UK Labour Market Insights: A Surface Freeze and Shifting Foundations

The UK labour market began 2026 under sustained pressure. Unemployment reached 5.2% in March—a four-year high—with an employment rate of 75% and an inactivity rate of 20.7% among those aged 16–64. A significant number of jobs were cut following the Chancellor’s Budget, and businesses froze recruitment amid tax uncertainty and rising employment costs.  

Yet beneath this cooling, significant shifts are emerging: young workers are abandoning white-collar careers for skilled trades, AI is creating roles in unlikely industries and the apprenticeship-versus-degree debate is fundamentally reshaping talent pipelines. 

Q1 2026 By the Numbers 

  • Unemployment: Rose to 5.2% in March 2026, sustaining a four-year high.
  • Employment Rate: 75% for those aged 16–64 (Q4 2025).  
  • Economic Inactivity: 20.7% for the 16–64 age group.  
  • Job Vacancies: Fell to 734,000 by March 2026, an 8.6% year-over-year decline.  
  • Wage Growth: Average weekly earnings growth decreased from 4.6% in January to 4.2% by March.  
  • Redundancies: Approximately 180,000 job losses followed the Chancellor’s Budget, with 84% of finance chiefs citing rising employment costs as their primary concern.  
  • Graduate Market: Graduate roles fell below 10,000 for the first time since 2016, marking a significant tightening at entry level.  

Top 4 Trends Shaping Q1 2026 

1. The Post-Budget Hiring Freeze 

Job growth in the private sector collapsed by 1.8% in November 2025 as businesses laid off staff at the fastest rate since the pandemic. The CBI Growth Indicator (Dec 2025) noted that private sector employers are accelerating job cuts and freezing recruitment in response to uncertainty around tax increases and spending cuts. In fact, 84% of finance chiefs cite rising statutory employment costs, including National Insurance increases, as their top concern. Despite this, there’s a glimmer of optimism: 13% of firms still plan to hire in the coming months, signaling a potential rebound. 

2. Apprenticeships are Out-Earning Degrees 

Young British workers are increasingly choosing manual and skilled trades over traditional white-collar careers, driven by two forces: AI displacement anxiety and superior economics. One in six employers expects AI tools to reduce headcount within the next year, pushing young workers toward roles less vulnerable to automation. 

For early careers talent, the financial case is compelling. Level 4 apprentices earn an average of £37,300 five years after qualifying (roughly £5,000 more than median graduates), without student debt. In fact, analysis shows that half of UK graduates would have earned more through higher-level apprenticeships. The squeeze at entry level makes this shift even more stark: in Q1, graduate roles fell below 10,000 for the first time since 2016. 

It’s no surprise then that the UK has slipped to 27th among OECD nations for youth employment, with youth unemployment at 15.3%—the highest since 2015. The government is responding with an £820 million investment to support nearly one million young people classified as not in education, employment or training (NEET), with Sir Keir Starmer calling for apprenticeships to be valued as highly as university degrees. 

3. The AI Implementation Gap Widens 

While AI continued to dominate headlines throughout Q1, the reality on the ground was sobering. According to Deloitte’s Finance Trends 2026 report, based on a survey of over 1,000 finance leaders, 63% have deployed AI solutions, while only 21% report seeing measurable value. More than half of firms have seen no revenue or cost benefits from AI to date. 

The UK sits at the sharp end of this paradox. Where AI is delivering, it’s delivering hard—the UK leads international peers in AI-driven productivity gains at 11.5% but also records the highest rate of net job losses due to the technology at 8%, double the international average. In other words, the organisations seeing returns see them at significant human cost, while the majority are still waiting to see any returns at all. The government’s response—training 10 million citizens in AI skills by 2030—signals recognition that the workforce implications can’t be left to employers alone. 

4. The Energy-AI Job Convergence 

Q1 revealed an unexpected source of job growth: the intersection of AI infrastructure and renewable energy transition. UK electricity network owners are hiring at their fastest pace since the 1950s to support the shift from fossil fuels and meet the power demands of AI data centres. 

Big Tech firms increased recruitment of energy specialists by 34% as electricity access becomes vital for expanding AI infrastructure. Skills in power procurement and grid interfacing are now in high demand as companies like Google and Amazon secure their energy future. Demand for specialists in AI, regulation and data reporting pushed UK financial sector vacancies up 12% in 2025 and continued into Q1 2026.  

What This Means for TA Leaders 

The apprenticeship-versus-degree debate has already been settled by the market. Graduate roles have fallen, while vocational talent is increasingly out-earning graduates. Your qualification filters (especially if they default to degrees) could be quietly narrowing your talent pool and handing an advantage to competitors who’ve already moved on. 

AI restructuring is a workforce planning problem, not just a technology one. The cuts already underway at major firms aren’t a warning of what’s coming—they’re evidence of what’s here. Organisations without proactive upskilling pathways for at-risk roles are already behind the curve. 

Energy and AI infrastructure skills are converging into a new talent scarcity. The intersection of renewable energy and AI data centre demand is creating competition for specialists that most organisations aren’t yet set up to hire for. Power procurement, grid interfacing and energy data skills are on the radar for organisations in sectors you wouldn’t expect.  

The hiring freeze is creating a talent access window that won’t stay open. With unemployment at a four-year high and 84% of finance chiefs in cost-containment mode, strong candidates are available now who weren’t six months ago. The organisations that move while competitors remain paralysed by uncertainty will emerge with significantly stronger teams. 

The UK labour market isn’t simply cooling—Q1 2026 demonstrated a fundamental restructuring around employment costs, AI capabilities and alternative career pathways. The organisations that recognized these shifts early and adjusted their talent strategies accordingly will be positioned for success as the market stabilises.